ARA Freight Market: Rate Turn Lower After a Long Climb, Then Barge Size Splits the Market


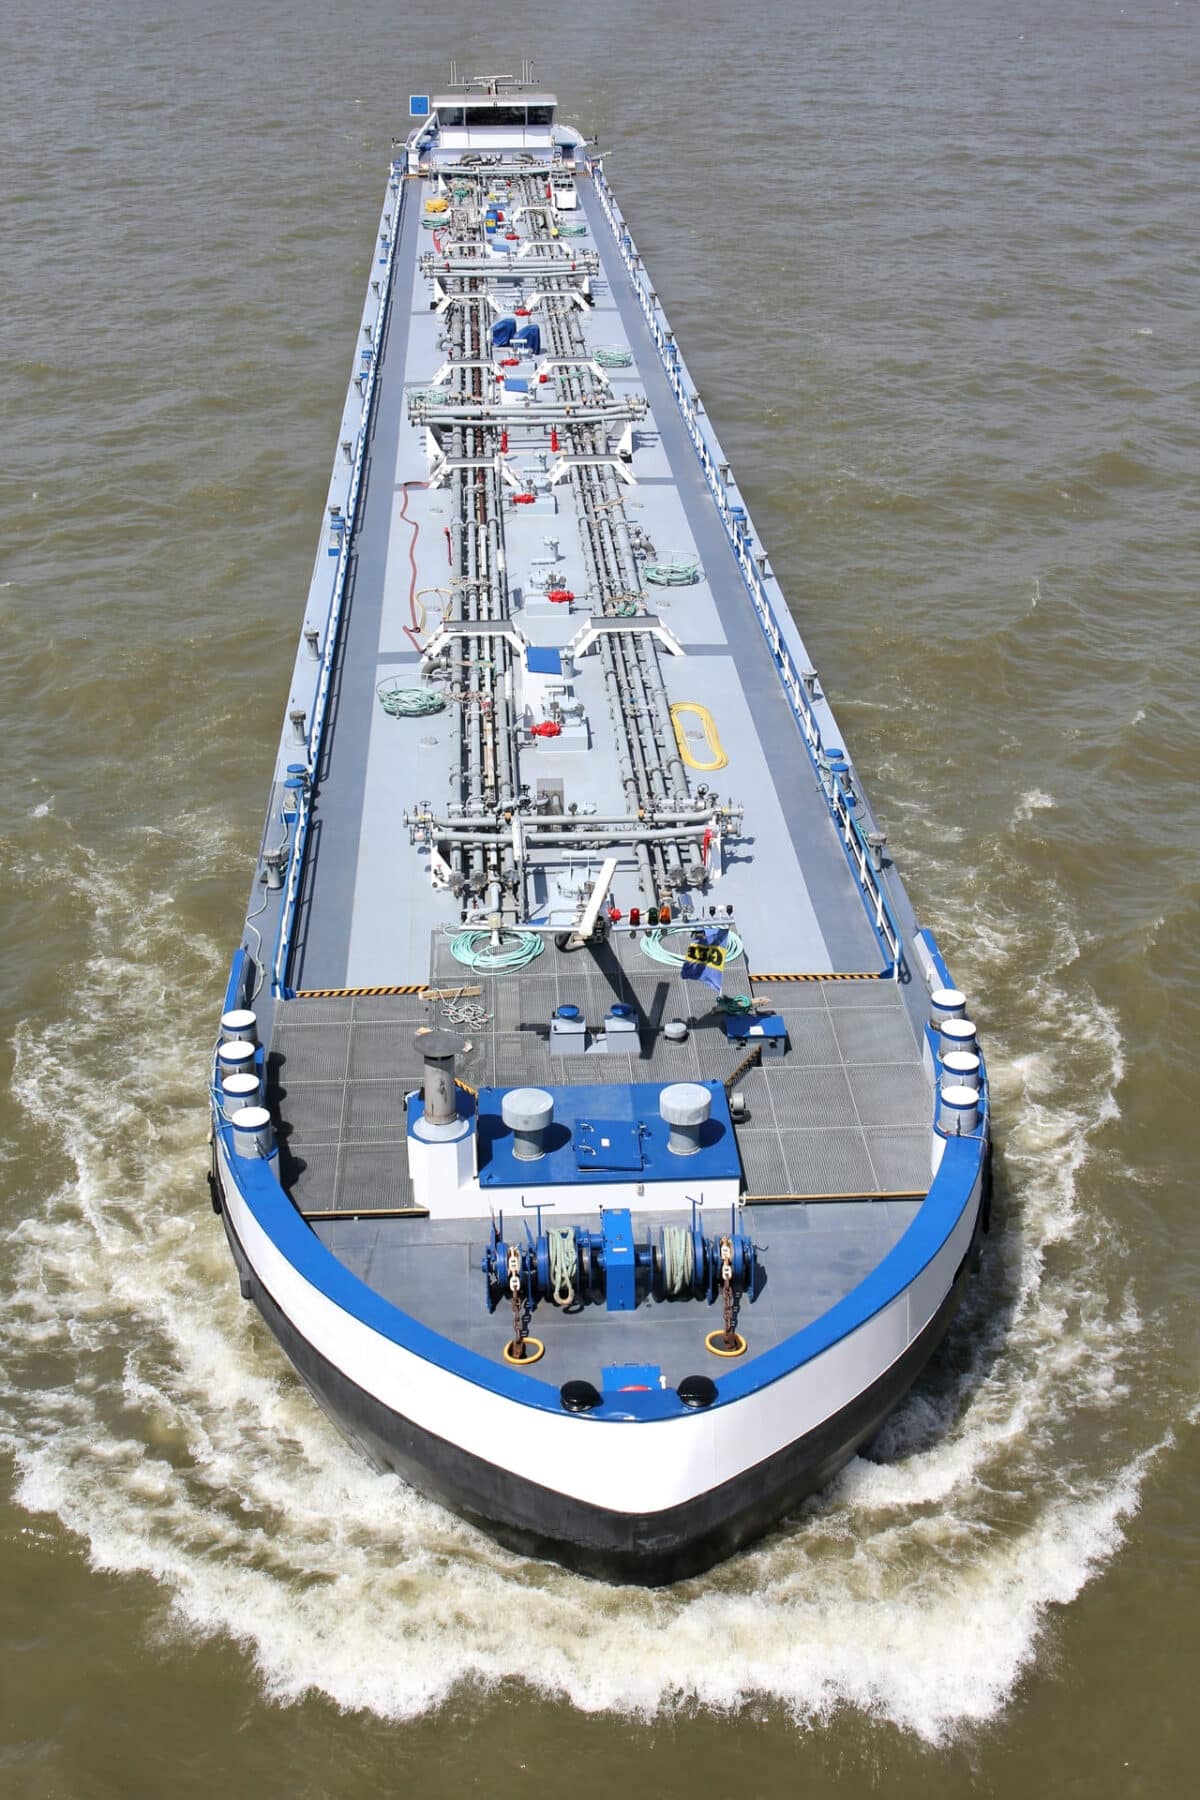
The ARA barge freight market showed its first real softening in weeks. After a long run of rising rates, both product segments eased on Tuesday. The rest of the week brought only small, selective changes. A storm over the weekend halted operations at several terminals, and its effects lingered through midweek. By Thursday and Friday, the main theme was barge size. Smaller barges stayed in demand and hard to find, while larger ones struggled to secure trips and some sat empty.

1. Freight Rates:  A Softer Tuesday, Then Small Selective Moves

Rates held on Monday and fell on Tuesday. After that, they changed only on a few routes.

  • 26 October: Rates held unchanged. Most prices were set on PJK B/L terms or at levels similar to the previous week.
  • 27 October: Rates turned lower. Middle distillates eased on the Rotterdam routes, and light ends dipped slightly on every route. Fixtures closed at lower levels in both segments, which marked a shift after the prolonged upward trend.
  • 28 October: A few middle distillate routes moved higher. Flushing to Amsterdam and Ghent to Amsterdam rose after fixtures closed at higher prices. All other routes held steady. No light ends deals were reported, so that segment stayed unchanged.
  • 29 October: Rates held on every route. One Antwerp to Amsterdam fixture closed at a higher level, but this was due to specific logistical requirements rather than stronger demand. The market treated it as an isolated case.
  • 30 October: Middle distillates stayed unchanged. Light ends rose on the Rotterdam to Amsterdam/Antwerp routes, and slightly on Ghent to Amsterdam, after some fixtures closed higher.

Takeaway: Tuesday’s dip was the main move of the week, and it was the first sign of easing pressure after a long climb. The rest of the week brought small adjustments, mostly in response to individual fixtures.


2. Spot Activity: Steady Volumes, Uneven Experiences

Activity stayed fairly even through the week, although operators described very different conditions depending on their fleets.

  • 26 October: The week opened on the high side for a Monday. Some freighters could not close new deals because trips from the weekend were delayed. Others had capacity and did more business. Most deals involved distillates such as jet fuel and gasoil, while light ends and renewables were fixed in smaller amounts.
  • 27 October: Activity stayed broadly stable. Operators spent time reorganizing schedules and renominating barges. Securing larger barges for middle distillates remained difficult, although some empty tonnage was reported.
  • 28 October: The market stayed active, with several incoming requests, but operators could accommodate only a few. Terminal delays held back available barges, so volume dipped even though demand for ships was stronger. Deals covered middle distillates and renewables such as HVO and FAME, with no light ends.
  • 29 October: Activity stayed steady. Deals were spread fairly evenly across product groups and mostly closed on PJK B/L terms.
  • 30 October: The week ended slightly slower. Demand stayed weaker for larger barges in both product categories, and some vessels were left empty.

Takeaway: The overall level of activity changed little. What differed was who could take part. Operators with smaller barges found business, while those with larger vessels did not.


3. Product Dynamics: Light Ends Ease, Then Recover

Middle Distillates

  • Held unchanged on Monday, with most business in jet fuel and gasoil.
  • Eased on the Rotterdam routes on Tuesday, as fixtures closed lower.
  • Rose on two routes on Wednesday, when a few fixtures closed higher. Rates stayed unchanged for the rest of the week.

Light Ends

  • Held unchanged on Monday, as fewer deals closed.
  • Dipped slightly on every route on Tuesday.
  • Saw no deals on Wednesday, then held steady on Thursday.
  • Firmed on Friday on selected routes after higher fixtures. Demand for smaller available barges supported this move.

Takeaway: Both segments softened together on Tuesday. Middle distillates then recovered on two routes, and light ends firmed late in the week.


4. Structural Drivers: Storm Disruption and a Barge-Size Divide

  • Storm disruption: A storm over the weekend halted operations at some terminals, mostly in Antwerp and to a lesser extent in Rotterdam and Amsterdam. Operators had to renominate trips and adjust loading times, and these delays continued to hold back barge availability through midweek.
  • Barge-size split: Smaller barges stayed in stronger demand and were hard to find. Larger barges struggled to secure trips, and several operators reported empty vessels, particularly for middle distillates.
  • Renewables demand: HVO and FAME featured in the week’s deals alongside diesel and gasoil, which showed ongoing demand for renewables.
  • Isolated fixtures: A few higher fixtures reflected specific routes or logistics rather than a broad change in demand. For that reason, they led to selective rate changes and not market-wide moves.

Takeaway: Terminal disruption from the storm and a mismatch between barge sizes and available cargoes shaped the week. This kept rates in a narrow range and made the market uneven rather than directional.


Conclusion

The ARA barge freight market eased this week after a long climb, with both segments dipping on Tuesday as fixtures closed at lower levels. Rates then changed only on a few routes, as middle distillates rose on two routes midweek and light ends firmed late in the week. A storm over the weekend halted operations at several terminals, mainly in Antwerp, and the resulting delays held back barge availability and forced renominations. Over the week, the market divided by vessel size. Smaller barges stayed in demand and hard to find, while larger ones struggled to secure trips and some stayed empty. Renewables such as HVO and FAME remained part of the daily business. The market now looks to next week to see whether larger barges find more work and whether the softer tone of Tuesday lasts.

What’s next?

Are you ready to face your challenges head-on?

We now offer a FREE customized trial to our BargeINSIGHTS tool, an all-in-one platform for liquid bulk barge transport optimization.

With BargeINSIGHTS, you get instant insights into barge freight rates, bunker gas oil prices, water levels, vessel tracking, and barge availability—all in one place. No more time-consuming data collection; everything you need is at your fingertips.

Click here to schedule your demo and get access to BargeINSIGHTS for free!
Rhine Freight Market: The Window of Better Water Closes as Swiss Diesel Supply Tightens


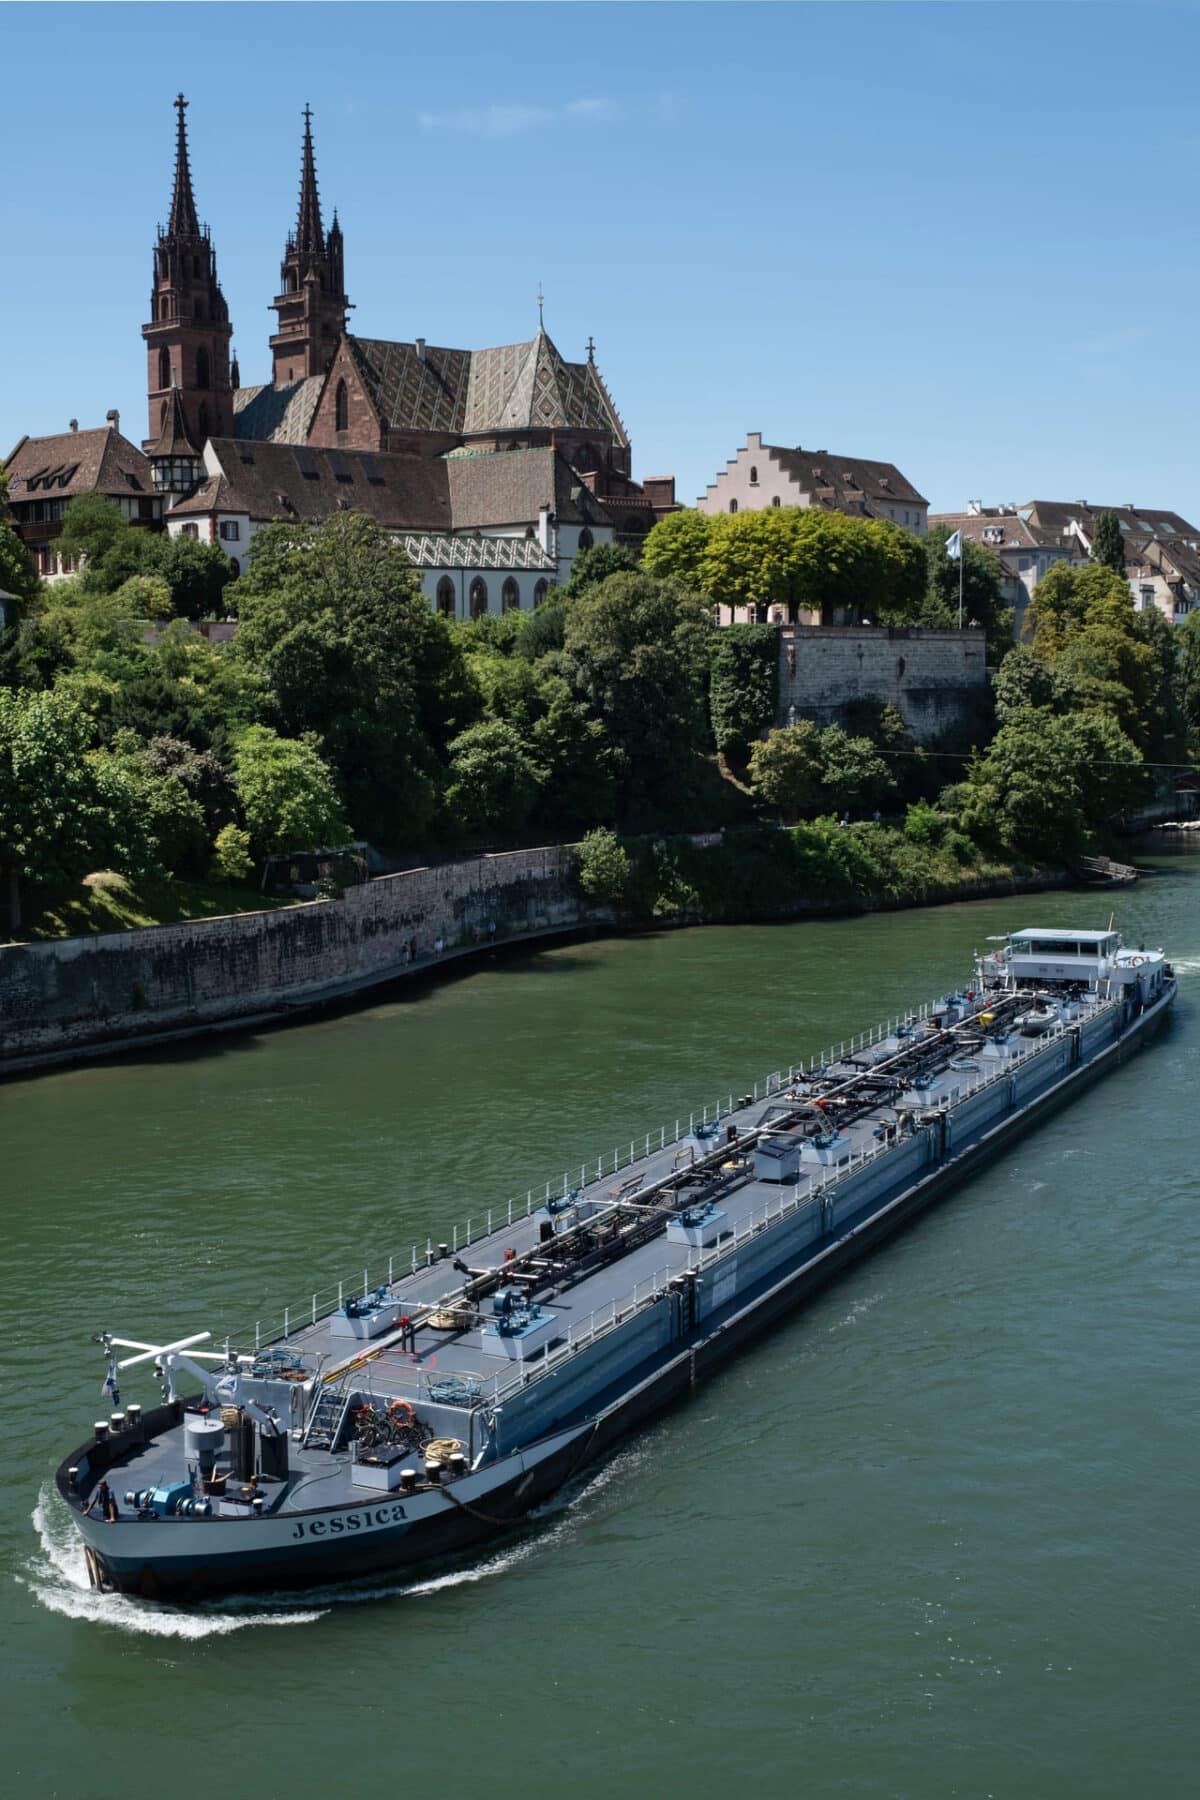
The Rhine barge freight market spent the week watching a short window of better water levels close. Early on, a storm in the ARA disrupted terminals, and operators spent Monday reorganizing schedules. Charterers then briefly returned to the market on Tuesday. However, forecasts soon showed Maxau and Kaub falling again, and many charterers withdrew. Rates moved only on a few Upper Rhine routes, while the Lower Rhine stayed unchanged. A separate supply story added to the concern, because Swiss-grade diesel deliveries from the Bottrop refinery were announced to stop for November.


1. Freight Rates: Small Adjustments on the Upper Rhine


Rates stayed unchanged on the Lower Rhine all week. The few changes came on Upper Rhine routes.

  • 26 October: Rates held on every route. Trading was limited, so there were no new price indications.
  • 27 October: Frankfurt and Karlsruhe eased, and Basel moved higher. Spot deals closed both above and below earlier levels, so rates were adjusted to reflect the average. Lower Rhine routes and Strasbourg stayed unchanged.
  • 28 October: Basel rose again. Deteriorating water forecasts raised the cost of moving cargo upstream, which put upward pressure on rates. All other routes held steady.
  • 29 October: Rates held. Spot deals closed in line with earlier publications, even though water levels were falling.
  • 30 October: The week closed with rates unchanged. A single deal gave too little evidence to justify any adjustment.

Takeaway: Rates moved only on a few Upper Rhine routes, mainly Basel. Everywhere else, thin trading left little evidence to change them, even as the water outlook worsened.


2. Spot Activity: One Livelier Day in a Calm Week

Activity stayed low all week, apart from a short pickup on Tuesday.

  • 26 October: The week opened calmly. Operators focused on reorganizing schedules after the weekend storm, and demand was limited.
  • 27 October: Business increased. Some charterers wanted to book barges, and operators offered available barges to the spot market. Others stayed away because the window of better intakes looked to be over.
  • 28 October: Trading calmed again. Operators resolved delays in the ARA and planned their fleets for the coming days.
  • 29 October: Activity stayed at a similar level. Most operators already had their upcoming trips allocated. Charterers were receiving product from barges they had booked the week before, so they did not need more.
  • 30 October: The week closed quietly. Fleets were fully booked, and operators focused on logistical issues before the weekend.

Takeaway:  Both sides of the market were covered. Operators had full schedules and charterers had enough barges, so there was little room for new spot business.


3. Structural Drivers: Storm Disruption, Falling Water and Swiss Supply

  • Storm disruption in the ARA: A storm over the weekend disrupted several terminals and refineries, and some halted operations for up to two days. This pulled attention away from spot business early in the week. Operators also had to renominate barges to resolve delays. Recovery of terminal operations was seen as key to how quickly activity would pick up.
  • Falling water levels: After a brief improvement, both Maxau and Kaub were forecast to decline again. This discouraged bookings for Upper Rhine destinations, because lower intakes raise the cost per ton and cut the volume each trip can move.
  • Swiss diesel supply: On Wednesday, the Bottrop refinery announced that Swiss-grade diesel deliveries would stop for November and resume in December. Swiss stocks were already low, so this could add pressure. Alternative supply from Carbura may help, but market participants were unsure how much it could offset.
  • Barges already committed: Many barges had trips allocated for the coming days, which limited capacity for new spot business.

Takeaway: Falling water, ARA disruption and a possible Swiss diesel shortfall all pointed toward tighter Upper Rhine conditions. For now, a lack of fresh deals kept most rates unchanged.


4. Water Levels: A Short Improvement, Then Decline

  • Maxau peaked early in the week and then began to fall. By Friday it had dropped below its recent range, and forecasts pointed to further declines over the weekend.
  • Kaub rose briefly at the start of the week, which eased restrictions for a short time. It then turned lower, and forecasts expected a further fall over the coming days.
  • Intakes shrank as levels fell. Barges sailing upriver still carried a fair load early in the week, but by Thursday loads to Upper Rhine destinations were limited, depending on barge size.

Takeaway: The improvement in water levels was short-lived. Falling gauges again limit loads to the Upper Rhine, and forecasts offer no clear relief.


Conclusion

The Rhine barge freight market had a quiet week in which a brief window of better water closed again. A storm in the ARA disrupted terminals and refineries at the start of the week, and operators spent much of the week resolving delays. Rates moved only on a few Upper Rhine routes, with Basel rising and Frankfurt and Karlsruhe easing, while the Lower Rhine stayed unchanged. Falling water levels at Maxau and Kaub discouraged Upper Rhine bookings, and the planned halt of Swiss-grade diesel deliveries from Bottrop through November added to concerns about Swiss supply. By Friday, fleets were fully booked and activity was limited to a single deal. The market now looks to Monday to see how operators judge water levels, achievable intakes and available barges.


What’s next?

Are you ready to face your challenges head-on?

We now offer a FREE customized trial to our BargeINSIGHTS tool, an all-in-one platform for liquid bulk barge transport optimization.

With BargeINSIGHTS, you get instant insights into barge freight rates, bunker gas oil prices, water levels, vessel tracking, and barge availability—all in one place. No more time-consuming data collection; everything you need is at your fingertips.

Click here to schedule your demo and get access to BargeINSIGHTS for free!
ARA Freight Market: FAME Tightness and Uneven Demand Keep Rates in a Narrow Band


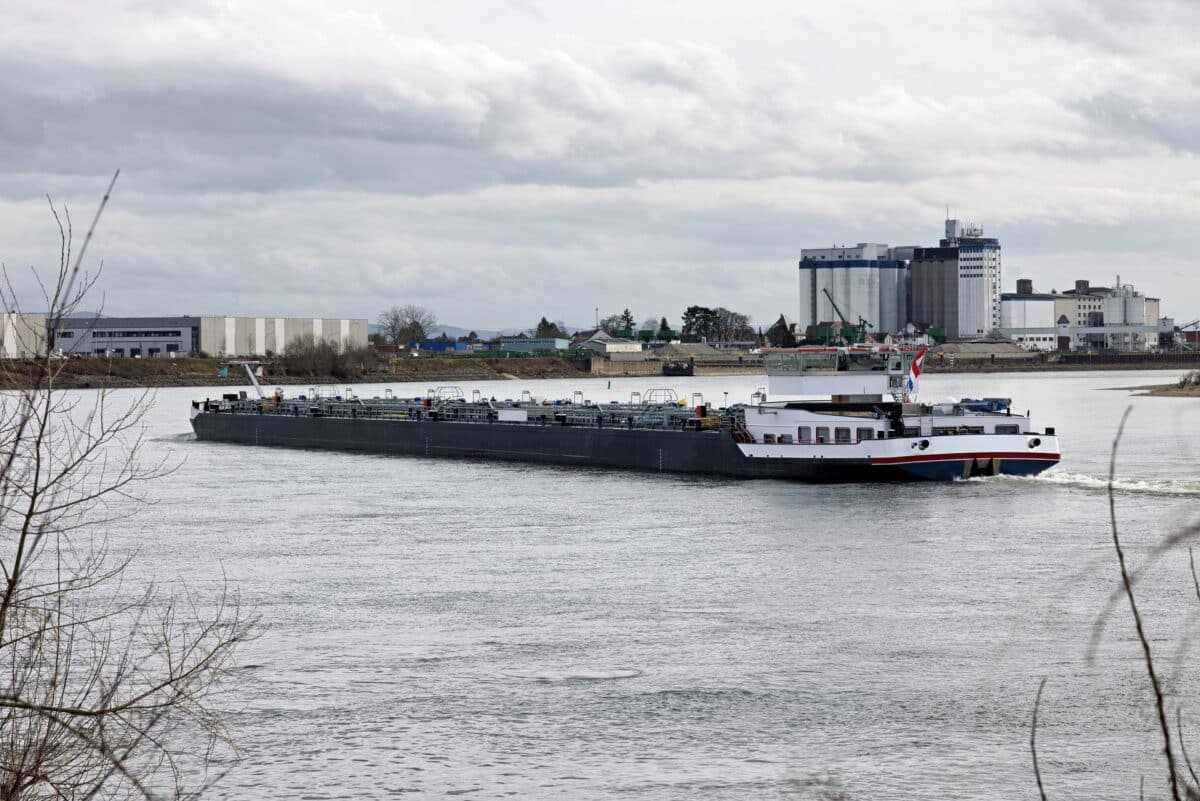
The ARA barge freight market moved within a narrow range this week. Rates changed slightly on a few routes and held steady on the rest. The more interesting story was underneath. FAME barges, especially the larger ones, were hard to find, while some light ends barges sat empty on Wednesday. Terminal delays kept vessels occupied through most of the week, so prompt availability stayed tight even when demand softened. Activity followed a clear rhythm. It was quiet on Monday, busier on Tuesday, softer on Wednesday, firmer on Thursday and quiet again on Friday.

1. Freight Rates:  Small Adjustments in Middle Distillates

Rates changed only slightly this week. Most of the movement came in middle distillates, and light ends moved just once.

  • 19 October: Middle distillate rates eased across the board after most deals closed at slightly lower levels. This narrowed the gap with light ends. Light ends held steady, as no new deals came through.
  • 20 October: Middle distillates showed a mixed picture. Rotterdam to Amsterdam/Antwerp rose the most, a few other routes edged up, and Ghent to Rotterdam dipped slightly. Light ends stayed completely unchanged, since all deals closed on standard terms or at the previous day’s levels.
  • 21 October: Fixtures on the Rotterdam to Amsterdam/Antwerp routes closed slightly higher. Both segments were adjusted on those routes, and all other routes held.
  • 22 October: Rates held, apart from a small rise for middle distillates on the Cross Harbor route. Most deals closed on standard PJK B/L terms, which gave little evidence of change, even though demand looked firmer.
  • 23 October: Rates held on every route. Only one deal closed at a slightly higher level, which was not enough to justify an adjustment.

Takeaway: The week brought small, selective rate changes. Middle distillates gave back a little at the start and then recovered on a few routes. Light ends moved once, on the Rotterdam routes, and otherwise held steady.


2. Spot Activity: Uneven Demand and Delays

Activity moved up and down from day to day, and delays shaped how much business operators could take.

  • 19 October: Activity was quiet at the start of the week. Delays over the weekend left barges stuck at terminals, so operators spent the day renominating them. All product categories were affected, but FAME barges faced the greatest difficulties.
  • 20 October: Business picked up well after the quiet start. Delays appeared to be easing, as fewer new problems were reported. Demand for renewables such as FAME and for distillates such as diesel was strong. Requests for light ends such as gasoline were fewer, although no empty ships were mentioned.
  • 21 October: Activity slowed midweek. Demand for spot barges weakened, and some vessels sat empty, particularly in the light ends segment. Operators found it harder to keep all barges employed, as terminal delays kept vessels occupied for longer trips.
  • 22 October: Activity picked up slightly. Requests for barges increased, and no empty vessels were reported. FAME was especially tight, as charterers struggled to secure available barges, particularly bigger ones.
  • 23 October: The week closed quietly. Demand was limited across both light ends and middle distillates, with few new requests. Barges stayed largely occupied because of terminal waiting times.

Takeaway: Demand came in waves, with stronger days on Tuesday and Thursday. Delays set the limit on how much business operators could take, so even softer days did not leave many barges idle.


3. Product Dynamics: Three Segments, Three Stories

Middle Distillates

  • Eased on Monday, as most deals closed slightly lower than in the previous publication.
  • Moved unevenly on Tuesday, with strength on the Rotterdam routes and mixed levels elsewhere.
  • Edged up on the Rotterdam routes again on Wednesday, then rose slightly on Cross Harbor on Thursday.
  • Held steady on Friday.

Light Ends

  • Stayed unchanged on most days, because many fixtures closed on standard terms or had no new deals.
  • Moved up slightly on the Rotterdam routes on Wednesday.
  • Saw weaker demand from Tuesday on. Some barges stayed empty on Wednesday, and demand remained limited on Friday.

Renewables

  • Faced the biggest problems with delays at the start of the week.
  • Drew strong demand on Tuesday and stayed especially tight on Thursday. Charterers struggled to secure larger barges.

Takeaway: Each product group had its own pattern. Middle distillates saw the small rate changes, light ends faced softer demand, and FAME showed the clearest signs of tight supply, particularly for bigger barges.


4. Structural Drivers: Terminal Delays and Barge-Size Mismatch

  • Terminal delays: Delays hit the market at the start of the week and kept barges occupied afterward. Chane Terminal Botlek, Sea Tank Ghent, Vesta Vlissingen and Esso Antwerp were among the terminals mentioned on Monday. Delays eased briefly on Tuesday, but waiting times continued to keep barges busy through Friday.
  • FAME supply: Delays hit FAME barges hardest. As a result, larger FAME barges became hard to secure, and charterers had difficulty finding vessels.
  • Uneven demand: Strong demand for FAME and diesel contrasted with weaker demand for gasoline cargoes. Some light ends barges stayed empty in midweek.
  • Limited price evidence: Many deals closed on standard PJK B/L terms. This gave few rate-per-ton indications, so rates changed little despite firmer demand on some days.

Takeaway: Delays and a mismatch between barge types and demand shaped the week. Tight FAME supply and softer light ends demand pulled in different directions, which kept overall rate changes small.


Conclusion

The ARA barge freight market had a steady but uneven week. Middle distillate rates eased on Monday and then edged up on a few routes, while light ends rose once, on the Rotterdam routes. Terminal delays at several locations kept barges occupied and limited prompt availability, even on days when demand softened. FAME stood out for tight supply, particularly for larger barges,while some light ends barges stayed empty in midweek. Most fixtures closed on standard terms,
so there was little fresh price evidence, and rates stayed in a narrow band. The market now looks to next week to see whether terminal delays ease and whether demand for FAME and diesel stays firm.

What’s next?

Are you ready to face your challenges head-on?

We now offer a FREE customized trial to our BargeINSIGHTS tool, an all-in-one platform for liquid bulk barge transport optimization.

With BargeINSIGHTS, you get instant insights into barge freight rates, bunker gas oil prices, water levels, vessel tracking, and barge availability—all in one place. No more time-consuming data collection; everything you need is at your fingertips.

Click here to schedule your demo and get access to BargeINSIGHTS for free!
Rhine Freight Market: Rates Step Down as Water Levels Finally Start to Rise


The Rhine barge freight market turned a corner this week. After a long stretch of restricted intakes, forecasts began to point to a real rise in water levels at Maxau and Kaub. Operators grew more confident about loading larger volumes, and rates eased in two stages. Lower Rhine rates fell first, on Tuesday. Upper Rhine rates followed on Wednesday, with the largest cuts of the week. Rates on most routes then held steady, as barge capacity stayed tight and operators stayed cautious. Many fleets were already booked well into the following week.


1. Freight Rates: Lower Rhine Eases First, Upper Rhine Follows


Rates held on Monday, then stepped down on Tuesday and Wednesday. They were broadly stable for the rest of the week.

  • 19 October: Rates stayed at their elevated levels. No deals closed, even though charterers were keen to move product up the Rhine. Operators were busy resolving delays, so barges were hard to find.
  • 20 October: Lower Rhine rates eased, with Cologne seeing the biggest cut. Forecasts for rising water at Maxau and Kaub made operators more confident about nominating higher volumes. Frankfurt and the Upper Rhine routes held steady for the time being.
  • 21 October: Upper Rhine rates dropped sharply, with Karlsruhe and Strasbourg falling the most and Basel following. Deals for these destinations closed at several price points, some lower and some equal to the previous day, so rates were adjusted to the average. Lower Rhine and Frankfurt rates stayed unchanged.
  • 22 October: Rates held on every route. Spot deals closed on standard PJK B/L terms or at levels similar to the day before, and participants described the market as stable.
  • 23 October: The picture was mixed. Duisburg, Dortmund and Cologne eased further, while Karlsruhe edged up. Frankfurt, Strasbourg and Basel stayed unchanged. Deals for the Lower Rhine closed at reduced levels, while Upper Rhine deals were stable or slightly higher.

Takeaway: Rates fell in two steps, led by the expected recovery in water levels. By Friday, the Lower Rhine was still drifting lower. The Upper Rhine had found some support, because intakes there remain limited until the water actually arrives.


2. Spot Activity: Busiest Midweek, Capacity-Limited Throughout

  • 19 October: Spot business was not the focus on Monday. Operators dealt with delays in Amsterdam, Duisburg and Gelsenkirchen, and no deals were finalized, although charterers were interested.
  • 20 October: Activity increased. Operators were active in securing trips, but many barges continued to sail under contract work as participants moved volumes ahead of the expected water improvement.
  • 21 October: More deals closed. Charterers wanted to secure barges to import product before the water rose. Some freighters closed several deals, while others were already fully booked and ignored spot business.
  • 22 October: The market turned slightly quieter after the busy session. Some charterers were still looking, but their requests often could not be met for lack of barge capacity.
  • 23 October: Activity stayed similar to the day before. Operators had covered their fleets over the weekend and were not rushing into new business. Charterers preferred to wait and see how water levels developed.

Takeaway:  Demand for barges stayed healthy all week, and capacity was the limiting factor. Trading was busiest early and midweek, then slowed as fleets filled up and charterers waited for better water.


3. Structural Drivers: Better Forecasts, Tight Capacity

  • Water forecasts improved. For the first time in weeks, both Maxau and Kaub were expected to rise meaningfully. By Friday, rain over the weekend was expected to support much higher intakes the following week. Operators nominated larger volumes in response, and this put downward pressure on rates per ton.
  • Forecasts remained unreliable. Predictions changed from day to day, and the accuracy of earlier forecasts had disappointed before. As a result, freighters stayed conservative about intakes, and some Upper Rhine trips remained restricted.
  • Barge supply stayed tight. Delays in Amsterdam, Duisburg and Gelsenkirchen kept vessels occupied. Many barges worked under contract, and operators often had their schedules completed through the weekend and into the next week.
  • Canal disruption added a new risk. Some locks on the Dortmund-Ems Canal were closed. Certain locks on routes toward Bremen were also expected to close for two weeks, which could cause further delays in that region.
  • Charterers turned selective. Late in the week, many buyers preferred to wait for the water to rise before booking, rather than pay current levels.

Takeaway: The market moved from scarcity driven by low water toward cautious optimism. Tight barge supply and unreliable forecasts kept the shift gradual rather than sudden.


4. Water Levels: A Recovery Takes Shape

  • Maxau hovered near its recent low early in the week. Forecasts then pointed to a clear rise toward the following week, with a peak expected before it declines again.
  • Kaub started the week low and rose steadily. Forecasts expected it to climb well above recent levels over the coming days, which would ease a key bottleneck for Upper Rhine trips.
  • Lower Rhine gauges such as Ruhrort also increased overnight on Thursday and were expected to rise further.
  • Rainfall was forecast over the weekend, which supported expectations of higher intakes next week. However, operators noted that these forecasts had shifted before.

Takeaway: Water levels are finally moving in the right direction. Operators will believe in the recovery only once the gauges confirm it, so they are loading cautiously for now.


Conclusion

The Rhine barge freight market eased this week as a long-awaited rise in water levels came into view. Rates fell on the Lower Rhine on Tuesday and on the Upper Rhine on Wednesday, then held steady until Friday, when the Lower Rhine eased again and Karlsruhe edged up. Barge supply stayed tight throughout, with terminal delays, contract work and full fleets limiting how much spot business operators could take. Forecasts for Maxau and Kaub improved, but operators
stayed conservative after earlier predictions fell short. Lock closures on the Dortmund-Ems Canal and the routes toward Bremen add new complications for barge transport in the coming weeks. The market now enters next week waiting to see whether rain and rising water translate into the higher intakes that forecasts promise.


What’s next?

Are you ready to face your challenges head-on?

We now offer a FREE customized trial to our BargeINSIGHTS tool, an all-in-one platform for liquid bulk barge transport optimization.

With BargeINSIGHTS, you get instant insights into barge freight rates, bunker gas oil prices, water levels, vessel tracking, and barge availability—all in one place. No more time-consuming data collection; everything you need is at your fingertips.

Click here to schedule your demo and get access to BargeINSIGHTS for free!
ARA Freight Market: A Record-Setting Thursday Stands Out in an Otherwise Steady Week


The ARA barge freight market had one clear peak this week. Trading volume built gradually through midweek, then surged on Thursday to its busiest session in months. Rates told a calmer story. Both segments rose together on Tuesday, middle distillates edged up again on Wednesday, and the surge on Thursday produced only small, mixed adjustments. Business then dried up on Friday as most operators had covered their schedules. Terminal delays continued to limit prompt availability throughout, and operators described demand as uneven between larger and smaller barges, and between product groups.

1. Freight Rates:  One Shared Move, Then Small Adjustments

Rates stayed flat on Monday. They rose across the board on Tuesday, after which changes were small and limited to middle distillates.

  • 12 October: Rates held at the start of the week. Almost all fixtures closed on standard PJK B/L terms, with only one lump-sum deal, so there was little new price evidence.
  • 13 October: Both segments rose by the same amount on nearly every route. Deals closed at higher levels in each product category. The one exception was Flushing to Rotterdam for middle distillates, which rose by a smaller amount.
  • 14 October: Middle distillates edged higher on most routes, while the Ghent routes held steady. Light ends stayed unchanged.
  • 15 October: Rates gave a mixed picture. Light ends stayed broadly in line with the previous day. Middle distillate fixtures closed both higher and lower, so Cross Harbor rose slightly, the Rotterdam routes eased slightly and the other routes held.
  • 16 October: Rates held unchanged. The few deals that closed were all on standard terms.

Takeaway: Tuesday brought the week’s only broad rate move. After that, the market digested higher levels with small, selective adjustments in middle distillates, and light ends held firm.


2. Spot Activity: A Steady Build, a Thursday Surge and a Quiet Friday

Activity stayed modest for most of the week and picked up only on the last day.

  • 12 October: Volume opened at a solid level, similar to the end of the previous week. Demand for middle distillate barges looked weaker, and some barges sat empty. Light ends saw more business, and available barges there were booked rather than left idle.
  • 13 October: Activity picked up slightly. Some operators reported normal demand and full fleets. Others struggled to find trips, especially for larger barges.
  • 14 October: Volume rose further to its highest level in about three weeks. The expiry of the October ICE gasoil contract helped drive business, which centered on middle distillates and renewables. Light ends were slower, and some operators struggled to find new cargoes.
  • 15 October: Activity surged to the busiest session since mid-May. Demand for barges strengthened, and vessels returning from earlier trips added available tonnage. This allowed operators to close many more fixtures, spread fairly evenly across all products.
  • 16 October: Trading slowed sharply. After Thursday’s surge, most operators had covered their schedules and showed little interest in fresh spot business before the weekend. Activity was expected to resume on Monday.

Takeaway: Volume climbed steadily to a standout Thursday and then fell away. Barges returning from earlier trips fueled the surge, and the quiet Friday suggests that surge pulled forward much of the week’s available business.


3. Product Dynamics: Middle Distillates Lead, Light Ends Linger

Middle Distillates

  • Held flat on Monday, as demand looked weaker and some barges stayed empty.
  • Rose on Tuesday and edged higher again on Wednesday, supported by the contract expiry and by renewables business.
  • Showed mixed fixtures on Thursday, with some deals higher and others lower. Rates adjusted slightly on a few routes.
  • Held flat on Friday.

Light Ends

  • Held flat on Monday, although this segment saw more activity than middle distillates, and available barges were booked.
  • Rose on Tuesday along with middle distillates.
  • Stayed unchanged from Wednesday through Friday. Wednesday’s commentary noted that some players struggled to find new cargoes in this segment, which could mean exports out of the ARA are finally slowing.

Takeaway: Both segments rose together on Tuesday, but middle distillates then took the lead in rate changes. Light ends held their level, even as demand there looked softer by midweek.


4. Structural Drivers: Delays, Uneven Demand and Returning Tonnage

  • Terminal delays: Waiting times continued at various terminals. Barges needed extra time to load or discharge, and operators had to renominate them. This limited prompt availability and made fresh spot business harder to secure.
  • Contract expiry: The October ICE gasoil expiry was mentioned at the start of the week as unlikely to change demand much. By Wednesday, however, it had helped lift volumes in middle distillates and renewables.
  • Uneven demand: Experiences differed from operator to operator. Some had full schedules until after the weekend, while others struggled to find trips, especially for larger barges and light ends.
  • Returning tonnage: Vessels coming back from earlier trips increased available barges on Thursday. This let operators close many more fixtures and explains the sharp volume surge.
  • Possible export slowdown: Market participants noted that weaker light ends demand could mean exports from the ARA ports are finally slowing.

Takeaway: Delays kept barges tight, but returning tonnage and the contract expiry opened a window of strong activity. Uneven demand between segments and barge sizes kept the market from moving in one clear direction.


Conclusion

The ARA barge freight market had a steady week with one standout day. Rates rose together in both segments on Tuesday, middle distillates edged higher on Wednesday, and Thursday’s busiest session in months brought only small and mixed rate adjustments. Terminal delays continued to limit prompt availability, while the October ICE gasoil expiry added some support to middle distillates and renewables. Light ends held their level all week, even though some players struggled to find new cargoes. By Friday, most operators had covered their schedules and trading slowed sharply. The market now looks to Monday to see whether the Thursday surge was a one-off or the start of a busier period.

What’s next?

Are you ready to face your challenges head-on?

We now offer a FREE customized trial to our BargeINSIGHTS tool, an all-in-one platform for liquid bulk barge transport optimization.

With BargeINSIGHTS, you get instant insights into barge freight rates, bunker gas oil prices, water levels, vessel tracking, and barge availability—all in one place. No more time-consuming data collection; everything you need is at your fingertips.

Click here to schedule your demo and get access to BargeINSIGHTS for free!
Rhine Freight Market: Promised Water Waves Fade and Rates Stay in a Narrow Range


The Rhine barge freight market moved sideways this week. Operators hoped rainfall would lift water levels and allow fuller loads. Instead, each forecast improvement came with a catch, and the second wave of water expected for later in the month disappeared from the outlook by Friday. Kaub stayed too low for most Upper Rhine trips, so operators and charterers focused on the Lower Rhine. Rates on a few of those routes edged up and down by small amounts, while most routes did not move at all. Congestion at canal locks and terminals added to the friction.


1. Freight Rates: Small Moves on the Lower Rhine


Rates held on most routes all week. The few changes came on Lower Rhine routes, where demand was strongest and sailing conditions were least restrictive.

  • 12 October: The week opened quietly, with only one inland trip registered. Market participants had hoped for rainfall to ease the pressure, but forecasts offered little relief. Both Maxau and Kaub were expected to decline further. Operators therefore focused on the Lower Rhine, and rates stayed unchanged.
  • 13 October: Duisburg and Dortmund rose. The expiry of the October ICE gasoil contract spurred importers to book barges. Some chose barges loading at inland sites, while others moved product from the ARA to Lower Rhine depots. Other routes held steady.
  • 14 October: Rates held. Some negotiations took place for Lower Rhine destinations, but many operators had already nominated their fleets. As a result, few new price indications emerged.
  • 15 October: Cologne and Basel eased slightly. Operators expected to load higher volumes as Maxau improved, and this pushed some quotes lower. Other routes stayed flat.
  • 16 October: Cologne moved higher after a single fixture closed above the published level. Rates on all other routes stayed stable, as operators planned to reassess conditions at the start of next week.

Takeaway: Rate changes were small and limited to a few routes. Strong demand and tight intakes pushed rates up, while the prospect of better water levels pulled them back down. The two effects largely cancelled each other out.


2. Spot Activity: Two Busy Days Between Quieter Sessions

Activity followed an uneven pattern. Two busier days, on Tuesday and Thursday, broke up a thin week.

  • 12 October: The week opened quietly, with just one inland trip registered. Operators spent the day assessing how falling water levels would affect barge availability and achievable intakes.
  • 13 October: Demand rose as the contract expiry drew importers into the market. Several deals were registered, mostly for Lower Rhine depots and inland loading sites.
  • 14 October: Trading slowed midweek. Many operators had already nominated their fleets in recent days, leaving limited capacity for new bookings.
  • 15 October: Activity more than doubled from the previous day, including some downstream trips. Most new fixtures went to the Lower Rhine. A few trips headed toward Basel, as operators anticipated better water levels at Maxau.
  • 16 October: The week closed with a single deal. Most fleets were already scheduled, so operators concentrated on organizing upcoming loadings and keeping barges busy.

Takeaway:  Demand was present, but barge availability set the pace. Fleets filled up quickly, so activity dropped off whenever fewer barges were free to book.


3. Structural Drivers: Water Forecasts, Congestion and Strong Demand

  • Water forecasts kept shifting. A small wave at Maxau promised better intakes. However, market participants remained cautious, because similar forecasts the week before had fallen short.
  • Kaub remained the bottleneck. It stayed low all week and kept most Upper Rhine trips from the ARA and Bottrop heavily restricted.
  • Demand for gasoil and diesel stayed firm. Swiss stocks remained low, which kept interest in Upper Rhine cargoes alive. In addition, the October ICE gasoil expiry drew importers into the market early in the week.
  • Congestion built up inland. Smaller barges rerouted through the Northern Netherlands and the Dortmund-Ems Canal faced delays at several locks.
  • Loading delays in the ARA also held back planning. Even when water levels improved slightly, operators could not raise their nominated volumes as much as they wanted.

Takeaway: Several constraints worked against each other. Strong demand and tight barge supply supported rates, while expected intake improvements and congested terminals limited the upside. The result was a market that moved little in either direction.


4. Water Levels: A Small Wave, Then a Disappearing One

  • Maxau: The gauge dipped early in the week, with forecasts pointing to a further decline. It then recovered, and by Friday it was expected to rise modestly over the weekend. Operators treated this with caution, given last week’s disappointment.
  • The second wave: On Thursday, forecasts showed another rise later in the month. By Friday, that wave had gone from the outlook. This removed the main hope for a more lasting improvement.
  • Kaub: The gauge stayed low and changed little, with only small movements expected in the coming days. As a result, intakes toward the Upper Rhine remained severely restricted.
  • Rainfall: Forecasts stayed unfavorable. Warm autumn weather and a lack of rain meant any gain would fade quickly.

Takeaway: Maxau may rise briefly, but Kaub offers little relief. Intakes toward the Upper Rhine will stay restricted, and the outlook for a lasting recovery has weakened.


Conclusion

The Rhine barge freight market had a steady but unsettled week. Rates changed only on a few Lower Rhine routes. Importer demand around the ICE gasoil expiry lifted some rates early in the week, while expectations of slightly higher intakes eased others later on. Water forecasts kept shifting, and the second wave that appeared on Thursday was gone by Friday. Kaub stayed low, loading delays continued in the ARA, and rerouted barges slowed at canal locks. In addition, Lower Rhine terminals began to fill up as inland movement stayed slow. Demand for gasoil and diesel remains strong, and Swiss stocks are still low. The market therefore enters next week watching whether any improvement at Maxau and Kaub can offset the current intake restrictions.


What’s next?

Are you ready to face your challenges head-on?

We now offer a FREE customized trial to our BargeINSIGHTS tool, an all-in-one platform for liquid bulk barge transport optimization.

With BargeINSIGHTS, you get instant insights into barge freight rates, bunker gas oil prices, water levels, vessel tracking, and barge availability—all in one place. No more time-consuming data collection; everything you need is at your fingertips.

Click here to schedule your demo and get access to BargeINSIGHTS for free!
ARA Freight Market: Light Ends and Middle Distillates Take Turns Leading a Firmer Week


The ARA barge freight market firmed on most days this week. Middle distillates and light ends took turns driving it. Both segments rose on Monday. Middle distillates then led on Wednesday, light ends on Thursday, and middle distillates again on Friday. Rates held steady only on Tuesday. Terminal delays kept barges tied up throughout, and smaller Rhine barges that had moved into the ARA added little relief.

1. Freight Rates:  Gains on Four Days, With Leadership Rotating

Rates rose on Monday, paused on Tuesday, then climbed on each of the last three days. Each day favored a different segment.

  • 5 October: Both segments rose across most routes. Barges were hard to find, and some operators secured extra payments through premiums and minimum tonnage terms.
  • 6 October: Rates held unchanged. Most fixtures closed on standard terms, so there was little new price evidence.
  • 7 October: Middle distillates rose on every route, as most fixtures closed at higher levels. No light ends fixtures were reported, so that segment stayed flat and the gap between the two widened.
  • 8 October: The lead switched. Strong demand lifted light ends on every route, while middle distillates held steady.
  • 9 October: Middle distillates rose again on most routes, though Rotterdam to Amsterdam/Antwerp and Flushing to Rotterdam eased slightly. Light ends stayed flat on standard terms.

Takeaway: The week was firmer overall, but no single segment drove it. Each rise came from whichever segment saw the most fixtures that day.


2. Spot Activity: Subdued Midweek, Livelier Friday

Activity stayed modest for most of the week and picked up only on the last day.

  • 5 October: Demand for spot barges was somewhat subdued, partly because suitable barges were hard to find.
  • 6–8 October: Volume stayed at similar levels each day. Some operators had little demand for their barges, while others lost time slots to delays and had to renominate.
  • 9 October: Activity picked up in the final session, mostly in middle distillates. Some operators still sought trips for the start of next week. Others had full schedules and focused on renominations.

Takeaway: Volume changed little until Friday. The market was limited more by barge availability and delays than by demand.


3. Product Dynamics: Where the Business Went

Middle Distillates

  • Rose on Monday as the tight market lifted rates, then held on Tuesday.
  • Rose again on Wednesday, when most fixtures closed higher.
  • Held steady on Thursday, as some operators struggled to find trips.
  • Rose on most routes on Friday, when this segment took most of the bookings.

Light Ends

  • Rose on Monday, then held through Wednesday. Barges for this cargo stayed occupied, and no fixtures were reported on Wednesday.
  • Moved higher on Thursday, when most of the day’s bookings fell in this segment.
  • Held steady on Friday, as business slowed and fixtures closed on standard terms.

Takeaway: Barges for each product were busy at different moments. That made the rate moves uneven, with each segment strengthening on its own days.


4. Structural Drivers: Delays and Creative Terms

  • Terminal delays stayed the main constraint. Operators had to renominate barges after missing time slots, and this limited how much new business they could take on.
  • Smaller Rhine barges entered the ARA market. They mainly took small parcels of FAME and diesel, so they eased the squeeze only in part.
  • Tight availability changed how deals were struck. Some operators secured premiums or minimum-tonnage terms linked to barge size.
  • Some operators still had barges without work, particularly in middle distillates. Others were fully booked.

Takeaway:  Delays and uneven barge availability supported rates all week. They also meant the market never moved in one clear direction.


Conclusion

The ARA barge freight market had a firmer week, with rates rising on four of five days. Middle distillates and light ends took turns leading. Middle distillates moved on Wednesday and Friday, and light ends moved on Thursday. Terminal delays kept barges occupied, and some operators secured premiums and minimum-tonnage terms in the tight market. Smaller Rhine barges added some supply, but mostly for small parcels. Activity stayed modest until a busier Friday, when operators were split between looking for trips and renominating delayed barges. The market heads into next week with availability still tight and its direction depending on how quickly delays ease.

What’s next?

Are you ready to face your challenges head-on?

We now offer a FREE customized trial to our BargeINSIGHTS tool, an all-in-one platform for liquid bulk barge transport optimization.

With BargeINSIGHTS, you get instant insights into barge freight rates, bunker gas oil prices, water levels, vessel tracking, and barge availability—all in one place. No more time-consuming data collection; everything you need is at your fingertips.

Click here to schedule your demo and get access to BargeINSIGHTS for free!
Rhine Freight Market: Rates Step Back Midweek as a Small Water Wave Draws Cautious Interest


The Rhine barge freight market began the week at a standstill, with no deals on Monday. A small wave of water in the forecast then brought some charterers back. As a result, rates fell on Wednesday after several weeks of holding or rising. By Thursday, the picture had split. Lower Rhine rates eased further, while Upper Rhine rates firmed. Operators stayed careful, because the expected improvement at Maxau was revised lower and rainfall remained scarce.


1. Freight Rates: A Midweek Drop, Then a Regional Split


Rates held on Monday and Tuesday. They fell on Wednesday, then moved in different directions on Thursday.

  • 5 and 6 October: Rates stayed unchanged. Monday brought no deals at all, as operators dealt with weekend delays in the ARA. On Tuesday, a few deals came through, but demand was split. Falling product prices could encourage restocking. However, the wide gap between October and November contracts led some buyers to postpone.
  • 7 October: Rates dropped on every route, with the largest cuts on the Middle and Upper Rhine. The expected wave of water brought more clients back to the market. At the same time, operators heard lower indicative offers, and intakes were set to improve slightly.
  • 8 October: The market split. Duisburg, Dortmund and Cologne eased further, while Karlsruhe, Strasbourg and Basel moved higher. Frankfurt stayed unchanged. Upper Rhine business picked up slightly, even though the Maxau outlook weakened.
  • 9 October: Rates held. Most deals closed at similar levels.

Takeaway: Wednesday’s drop was the week’s main move. Thursday’s mixed picture shows how unsettled the market remains. Lower Rhine rates are drifting lower, while Upper Rhine rates are finding support from tight conditions.


2. Spot Activity: Silent Monday, Modest Recovery

Activity stayed low all week, but it improved after Monday.

  • 5 October: No deals were registered. Operators spent the day renominating barges stuck at ARA terminals.
  • 6–9 October: A handful of deals closed each day, with a small increase on Wednesday as the water forecast improved. Most operators focused on preparing their fleets and watching the water levels rather than on new business.

Takeaway:  Trading began from zero and recovered only slightly. Operators wanted more certainty on water levels before committing barges.


3. Structural Drivers: Timing Risk and Delays

  • The small wave of water gave the market some hope. However, intakes would still stay limited. Many operators did not want to risk getting stuck behind the shallowest points.
  • As a result, most barges stayed near the ARA, or went no further than Duisburg and Cologne, rather than taking longer trips upriver.
  • Terminal delays continued in the ARA, with Eurotank Amsterdam, ATPC and Evos Ghent mentioned early in the week. Staff shortages at Gelsenkirchen and Bottrop caused further waiting times. Barges at MiRO also waited for higher water before sailing upriver.
  • A lock closure on the Dortmund-Ems Canal slowed the smaller barges that use this route. The lock reopened by Friday, but another closure may follow next week.
  • Gasoil stocks in Basel stayed low. Some reserves may be released after a meeting on Monday.

Takeaway: Demand returned slightly, but delays and water-level timing risk kept barge supply short. That explains why cautious operators and slightly lower rates coexisted this week.


4. Water Levels: A Short-Lived Improvement

  • Kaub moved close to zero and slightly below it during the week. Forecasts pointed to a rise toward 25 by the following week.
  • Maxau forecasts changed several times. The expected peak was first revised lower, then settled around the weekend, with a decline expected afterwards.
  • Rainfall forecasts stayed poor, so operators expect any improvement to be short-lived.

Takeaway: Water levels may improve briefly, but the outlook stays fragile. Intakes will remain limited, particularly for the Upper Rhine.


Conclusion

The Rhine barge freight market had a cautious week. Monday opened without a single deal, and a small wave of water then drew some clients back. Rates dropped on Wednesday, and by Thursday Lower Rhine routes eased further while Upper Rhine routes firmed. Terminal delays, staff shortages and a lock closure on the Dortmund-Ems Canal kept barge supply short. Water levels were expected to improve only briefly, and operators kept most barges close to the ARA. Gasoil stocks in Basel remain low, and a meeting on Monday may bring more information on reserves. For now, the market heads into next week watching how the small wave of water translates into real intakes.


What’s next?

Are you ready to face your challenges head-on?

We now offer a FREE customized trial to our BargeINSIGHTS tool, an all-in-one platform for liquid bulk barge transport optimization.

With BargeINSIGHTS, you get instant insights into barge freight rates, bunker gas oil prices, water levels, vessel tracking, and barge availability—all in one place. No more time-consuming data collection; everything you need is at your fingertips.

Click here to schedule your demo and get access to BargeINSIGHTS for free!
ARA Freight Market: Middle Distillates Edge Higher on Monday, Then Rates Hold as Delays Limit Trading


The ARA barge freight market stayed quiet this week. Terminal delays kept barges tied up, and prompt availability stayed tight. Middle distillate rates rose on Tuesday. Otherwise, rates held steady, as most deals closed on standard terms. Trading slowed toward the end of the week.

1. Freight Rates:  One Uptick, Then Stable

  • 28 September: Most business closed on standard PJK B/L terms or as lump-sum deals. This gave little rate-per-ton evidence, so rates held unchanged.
  • 29 September: Middle distillate rates rose across the board. Light ends stayed mostly stable.
  • 30 September: Few rate-per-ton deals closed, and they matched the previous day’s levels. Rates held steady.
  • 1 October: Fixtures again closed mostly on standard terms. Rates stayed unchanged.
  • 2 October: The week ended quietly, and rates held steady.

Takeaway: Middle distillates firmed once, midweek, and then held. Light ends stayed stable all week.


2. Spot Activity: Brief Pickup, Then a Slow Fade

  • 28 September: Activity doubled from the previous session but stayed low overall, as delays limited new business.
  • 29 September: Activity improved further as operators looked ahead to the new month.
  • 30 September: Activity eased, as terminal delays limited how much new business operators could take on.
  • 1 October: Trading slowed further as the weekend approached.
  • 2 October: The week closed quietly, with most fleets already booked for the coming days.

Takeaway: Activity improved early in the week and then faded, as delays and booked-out fleets left little room for new business.


3. Product Dynamics: Middle Distillates Move, Light Ends Hold

Middle Distillates

  • Held flat on Monday, then rose on Tuesday as demand stayed firm.
  • Held steady from Wednesday onward, as no middle distillate fixtures were reported on Friday.

Light Ends

  • Stayed stable all week. Activity in this segment was limited.

Takeaway: Middle distillates saw the week’s only real move. Light ends stayed unchanged throughout.


4. Structural Drivers: Delays and Tight Availability

  • Terminal delays stayed the main constraint all week. Operators reported waiting times at several terminals, including Chane Terminal Botlek, Vopak Terminal Europoort and Evos Ghent.
  • Prompt barge availability stayed tight, because delays kept vessels occupied.
  • Some Rhine-based barges returned to the ARA because of low water levels. They mostly took smaller parcels and depot work.
  • Renewables made up most of the booked volume by the end of the week.

Takeaway:  Terminal delays and tight availability limited new business. This kept rates steady after Tuesday’s increase.


Conclusion

The ARA barge freight market had a quiet week. Terminal delays kept barges tied up and held back fresh spot business. Middle distillate rates rose once, on Tuesday, while light ends stayed unchanged. Some Rhine-based barges moved into the ARA because of low water levels, but they mostly took smaller parcels and depot work. Trading slowed toward the weekend, with most fleets already booked. Operators expect more negotiations next week as they look to secure additional trips.

What’s next?

Are you ready to face your challenges head-on?

We now offer a FREE customized trial to our BargeINSIGHTS tool, an all-in-one platform for liquid bulk barge transport optimization.

With BargeINSIGHTS, you get instant insights into barge freight rates, bunker gas oil prices, water levels, vessel tracking, and barge availability—all in one place. No more time-consuming data collection; everything you need is at your fingertips.

Click here to schedule your demo and get access to BargeINSIGHTS for free!
Rhine Freight Market: Lower Rhine Rates Edge Higher While Water Forecasts Turn Cautiously Optimistic


The Rhine barge freight market stayed quiet this week. Water levels remained extremely low, and Kaub reached a new record low. Rates for Lower Rhine destinations moved higher early in the week, while Upper Rhine routes saw only limited change. Activity stayed thin throughout. By Friday, forecasts pointed to a modest recovery in water levels, and rates held steady.


1. Freight Rates: Early Gains, Then a Steady Close


  • 28 September: Only a few deals closed. Rates for Karlsruhe and Strasbourg moved higher, while most other routes stayed unchanged.
  • 29 September: Activity picked up slightly, including several downstream trips. Fixtures for Lower Rhine destinations closed at higher levels, so rates for those routes rose.
  • 30 September: Business stayed at a similar level. Duisburg saw a small increase, and most other routes held steady.
  • 1 October: Most participants focused on closing their September books and waited for rainfall. Dortmund eased slightly, while the other routes stayed unchanged.
  • 2 October: The week ended quietly, and rates held at the previous day’s levels.

Takeaway: Rates firmed on a few routes at the start of the week, mainly in the Lower Rhine. They then stayed stable as little new business came to the market.


2. Spot Activity: Thin Trading From Start to Finish

  • 28 September: The week opened extremely calm, with very few deals.
  • 29 September: Activity improved slightly, helped by a few downstream trips.
  • 30 September: Volume stayed close to the previous day’s level.
  • 1 October: Trading stayed limited as participants closed the books on the previous month.
  • 2 October: Activity eased a little more. Most operators had already scheduled their fleets for the coming days.

Takeaway:  Spot activity stayed low all week. Operators found it hard to place barges, and charterers found it hard to source suitable tonnage.


3. Structural Drivers: Low Water and Cautious Buyer

  • Low water levels remained the main constraint. Operators struggled to find barges that could reach certain destinations, and they found it hard to plan achievable intakes.
  • Elevated diesel prices kept charterers hesitant. Uncertainty around the Strait of Hormuz added to this caution.
  • Diesel imports from the ARA were almost non-existent, so buyers had fewer ways to replenish stocks.
  • A temporary lock closure at Kostheim briefly restricted access to the Main and Raunheim. Operators resolved this within days.
  • Smaller barges found a workaround. They detoured through the Dortmund-Ems Canal and loaded larger volumes.

Takeaway: Low water, high fuel prices and scarce suitable tonnage kept the market cautious. Rates rose only where intakes were most restricted.


4. Water Levels: Record Lows, Then a Possible Recovery

  • Kaub fell to another record low during the week. Navigation past the gauge stayed close to impossible for many barges.
  • Maxau also touched a record low midweek, which further limited intakes.
  • The Kaub forecast shifted during the week. Early projections showed a deeper fall, but later outlooks pointed to a stabilisation.
  • By Friday, forecasts suggested a gradual rise at both gauges. Operators said any benefit would depend on timing and barge availability.

Takeaway: Water levels stayed critically low, but forecasts improved late in the week. The market now waits to see whether that translates into higher intakes.


Conclusion

The Rhine barge freight market had a quiet week. Low water levels kept both operators and charterers cautious, and Kaub and Maxau both reached record lows. Rates for several Lower Rhine routes edged higher early in the week, but most routes then held steady as trading stayed thin. Elevated diesel prices and limited import options added to the hesitation among buyers. Forecasts for rising water levels improved sentiment slightly by Friday. Some participants also expect stronger demand in the second half of October, so the market heads into next week watching whether higher intakes materialise.


What’s next?

Are you ready to face your challenges head-on?

We now offer a FREE customized trial to our BargeINSIGHTS tool, an all-in-one platform for liquid bulk barge transport optimization.

With BargeINSIGHTS, you get instant insights into barge freight rates, bunker gas oil prices, water levels, vessel tracking, and barge availability—all in one place. No more time-consuming data collection; everything you need is at your fingertips.

Click here to schedule your demo and get access to BargeINSIGHTS for free!